Clarity · Strategy · Security
Understand your retirement before anyone recommends anything to you.
You have spent decades building what you have. You deserve to know exactly how your income, your taxes, and your risks fit together — in plain language — before a single strategy is put in front of you.
Sierra Vista Wealth Strategies is an independent retirement planning practice in Texas. Kevin Holyfield, a Certified Financial Fiduciary®, teaches first and recommends second — and only when something genuinely fits your goals.
About 20 minutes. No cost, no paperwork, no products discussed — and no obligation to do anything afterward.
- Education before recommendation
- Independent — not owned by any product company
- Risk first, products last
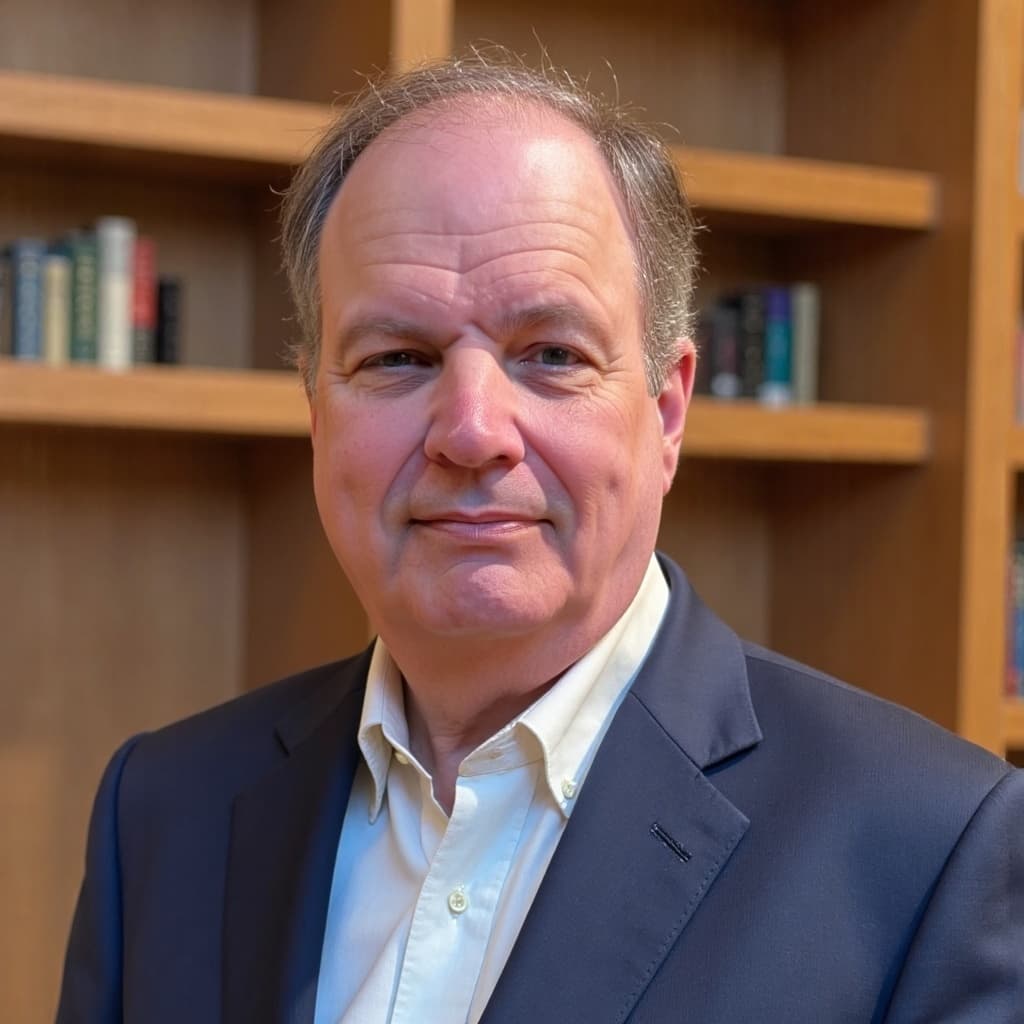
Kevin Holyfield, CF2®|Certified Financial Fiduciary®
The Sierra Vista approach
Education before recommendation.
This is the rule the whole practice is built on. You will never be asked to decide on something you do not already understand. If you cannot explain it back in your own words, the teaching is not finished — and nothing moves forward until it is.
We listen first
Before anything is explained or proposed, we want the whole picture — what you have built, what keeps you up at night, what you want retirement to actually look like, and who else depends on the answer.
We teach, in plain English
How retirement income really works. Where taxes show up later. What a bad market in your first few retired years can do to a plan. What each option costs, what it gives up, and what it protects. No jargon, and no slide deck built to sell you something.
Only then, a recommendation — if one fits
If a strategy genuinely serves your goals, you will see exactly why, what the trade-offs are, and what happens if you simply do nothing. And “you do not need this” is a perfectly normal place to land.
You are never asked to sign anything on the day you first hear about it. Take the information home. Talk it over with your spouse. Run it past your CPA or your attorney. The decision is yours, and it will keep until you are ready to make it.
Who you would be working with
About Kevin
Kevin Holyfield, Certified Financial Fiduciary®
Long before he worked in financial services, Kevin spent years as an entrepreneur in healthcare — helping patients, physicians, and organizations untangle complicated problems and make difficult decisions with a clear head. That is still more or less the job.
Over those years, friends, employees, and clients kept bringing him the same kind of question: about retirement, about income, about whether the thing someone was pushing on them was actually any good. What struck him was how few of them had ever been taught how their own money worked. They had been sold to. There is a difference, and for a retiree it is an expensive one.
So he became a financial professional focused on retirement planning, and built this practice around the opposite habit: teach first, recommend second, and only when something genuinely fits.
You will find him easy to talk to and hard to rush. He will not talk down to you, and he will not use a term he has not already explained.
- Certified Financial Fiduciary® (CF2®)
- Honors graduate of The University of Texas — two degrees
- Based in Texas
My philosophy is simple: listen first, education before recommendation, and solutions only when they truly align with a client's goals and best interests. As a Certified Financial Fiduciary®, I am committed to putting my clients' interests first and helping them make informed decisions with confidence.
Independence & risk-first planning
No parent company. No sales quota. No house product to move.
What independence actually means for you
Sierra Vista Wealth Strategies is independently owned. It is not a branch of a bank, a carrier, or a national brand with a shelf of in-house products that need to move this quarter.
So the options you are shown are narrowed by one thing only: your situation. It also means Kevin is free to give you the answer nobody makes money on — “leave it exactly as it is.”
As a Certified Financial Fiduciary®, Kevin is committed to putting your interests ahead of his own. And before you decide on anything at all, you will be told plainly how he is compensated if you move forward.
Why the conversation starts with risk
Retirement plans rarely fail because the upside was too small. They fail on the downside. So we start at that end — what could go wrong, how likely it is, and what it would actually cost you:
- A bad market in your first few retired years
- Outliving your savings
- Taxes you have not accounted for yet
- The cost of a long-term care event
- Inflation across a 25- or 30-year retirement
- What the surviving spouse is left with
Once we know which of those would genuinely hurt you, and by how much, the rest gets simple: protect against those first, then grow what is left with the money you can afford to put at risk.
Who we help
Where you are right now
The right conversation depends far less on your age than on which stage you are in. Tell Kevin which of these sounds like you, and that is where things start.
You are still building.
You have earning years ahead, and you would like more of what you set aside to survive the tax bill waiting at the other end. The work here is accumulation with the taxes thought through in advance — so that the version of you who retires has options instead of constraints.
- Tax-advantaged and tax-free accumulation strategies
- Keeping your options open as your income and the tax code change
- Protecting your family while you are still the one earning
You are approaching — or already in — retirement.
The question quietly changes from “how much do I have” to “how long will it last, and what could break it.” The work here is protecting what you spent decades building and turning it into income you can actually rely on.
- Reliable retirement income, often through annuity-based strategies
- Protecting principal from a bad market at the worst possible time
- Shedding risk you are carrying without being paid to carry it
- Planning ahead for long-term care costs
- Making sure you do not outlive your savings
You have a decision sitting in front of you.
A 401(k) rollover, a pension election, a severance package, an inheritance, or a proposal somebody handed you that you do not fully follow. Most of these are one-way doors. They are worth understanding completely before you walk through one.
- What each option actually does, in plain language
- What it costs you and what it gives up
- What happens if you simply do nothing
Annuities, explained
A tool for a specific job — not the answer to everything.
Annuity-based strategies are among the most useful instruments available for building protected retirement income, and among the most misunderstood. Some are excellent at one particular job. Some are expensive and inflexible. The only way to know which is which for you is to understand how they actually work — so that is what Kevin walks you through, long before he would ever suggest one.
What the right one can do for you
- Pay you an income stream you cannot outlive
- Shield principal from a market downturn at the wrong moment
- Grow on a tax-deferred basis until you draw on it
- Leave a surviving spouse a predictable floor to stand on
What you should know going in
- Your money is less liquid — most contracts carry a surrender period
- Guarantees depend on the claims-paying ability of the issuing insurance company
- Features and riders cost money, and those costs should be shown to you in dollars
- An annuity is almost never the right home for all of your savings
If, once you understand all of that, an annuity does not fit your situation — Kevin will tell you so plainly. That happens regularly, and it is not a wasted conversation. You will still walk away knowing how the thing works the next time someone brings one to you.
Your first call
Exactly what happens — and what doesn't.
Calling a financial professional for the first time should not feel like a risk. So here is the whole thing in advance. It is one phone call, it runs about twenty minutes, and you can end it whenever you like.
- ~10 min
You talk. Kevin listens.
Where you are, what you have built, and what is actually worrying you. Nothing to prepare — no forms, no statements, no numbers to dig up beforehand.
- ~5 min
You ask whatever you have been wondering about.
Income, taxes, timing, something you read, something another office told you. You get a straight answer, including when the honest answer is “that depends, and here is on what.”
- ~5 min
You decide if a longer conversation is worth your time.
If it is, we put one on the calendar. If it is not, the call ends warmly and that is genuinely the end of it.
What will not happen
- No products presented, quoted, or pitched
- No paperwork, applications, or signatures
- No request for account numbers or your Social Security number
- No pressure to book a second meeting
- No follow-up calls you did not ask for
- No cost, and no obligation of any kind
Most people finish the call knowing one or two things about their own money they did not know that morning. That is worth twenty minutes on its own — whether or not we ever speak again.
Schedule an Introductory CallGetting to know Kevin
Away from the office, Kevin is usually behind a camera, traveling with his wife Suzanne, or somewhere with his children and grandchildren. It is no accident that his work is about other people's families — he is thinking through the same questions for his own.
Contact
Start with a question, not a commitment.
You do not have to be ready to do anything. If there is one question you have been carrying around about your retirement, send it. Kevin answers his own email and his own phone.
Kevin Holyfield, Certified Financial Fiduciary®
Sierra Vista Wealth Strategies · Texas
What happens after you hit send
Kevin reads it himself and replies within one business day, usually sooner. No auto-responder, no call center, no drip campaign. Your details are never shared or sold, and if you would rather not hear from him again, saying so once is enough.
Not sure yet? Read exactly what happens on the introductory call before you reach out.